


ASIC has issued a warning to advice licensees: using or allowing lead generation services may put their licences at risk.
The warning comes alongside the regulator’s review of 15 licensees, covering January 2025 to June 2026. Across those licensees, lead generators referred 7,639 new clients, 35 per cent of all new clients. More than $678 million was switched or invested, about 90 per cent of it from superannuation funds. The licensees received $9.8 million in initial advice fees, and clients committed to a further $4.5 million in ongoing fees.
The review, published as Report 845, found unlicensed or unqualified lead generators involved in advice. Some licensees let them carry out specialist tasks such as fact-finding, risk profiling and discussing advice recommendations. ASIC also found some lead generators making potentially misleading, fear-based or non-like-for-like performance claims to encourage super switching.
In an accompanying statement, ASIC commissioner Alan Kirkland said the report “sends a clear warning to advice licensees”. Licensees “must ensure that only authorised advisers provide personal advice”, he said and “commercial incentives must not come at the expense of consumers”. ASIC “will continue to take enforcement action under current laws where we find evidence of serious consumer harm”.
Control weaknesses
ASIC identified several weaknesses in how licensees supervised these arrangements:
- limited access to lead generator call recordings;
- heavy reliance on manual supervision;
- insufficient monitoring of product recommendation patterns; and
- inadequate limits on adviser client volumes.
ASIC said licensees need to identify and prohibit arrangements that may compromise advice quality or expose consumers to harm, ensure advisers act in their clients’ best interests, and oversee what lead generators say to clients.
“Gap in the law”
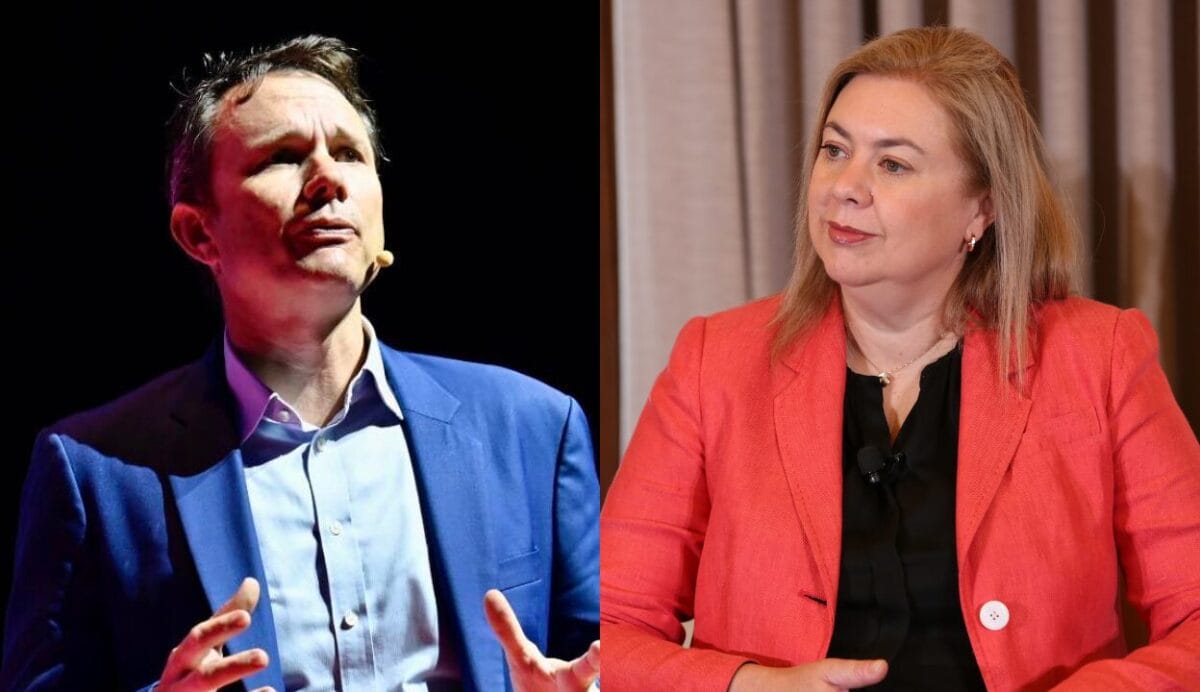
Super Consumers Australia chief executive Xavier O’Halloran said the ASIC review was “a decent review” and that the regulator “is doing what it can with the toolkit that it’s got and the resources that it’s got”. His criticism is aimed at the law.
“I think there’s a gap in the law here,” he tells Professional Planner. “Unless we have a stricter law that puts an end to this kind of practice altogether, we’re going to be constantly playing catch up.”
Super Consumers wants a complete ban on lead generation for super switching and financial advice. “We just don’t think it’s a useful part of the sector, and we don’t see good financial advisers using it,” O’Halloran says. He argues that “managing this problem through more law and regulation may not get it done”. He describes the Government’s current proposal as one that “looks at licensing and putting more obligations on the financial advice licensees” to manage the lead generators they use.
He points to the way lead generators are paid. ASIC’s report found that payment structures “varied between flat fees, success-based payments and fee sharing” and that in some arrangements the referral partner “could receive up to 100 per cent of the client’s initial advice fee”, contingent on the client converting. ASIC said that where payment depends on conversion or absorbs most or all of the upfront fee, it “creates a powerful sales incentive”.
“If the entire incentive is around switching, and they’re willing to give away 100 per cent of their fees to a lead generator that leads to a switch, that’s going to incentivise switching in scenarios where switching may not be the best advice for the individual,” O’Halloran says. He called it “a conflicted model that needs to be banned”.
O’Halloran previously told the 2025 Professional Planner Researcher Forum that after he responded to an Instagram ad, the lead generator flattered him and within 10 minutes of the call wanted to take him through the statement of advice, to get him to switch products.
Social media
O’Halloran also wants social media platforms held responsible for the ads that feed these schemes. “If it’s just down to the regulator to play a game of whack-a-mole whenever a bad advertisement pops up, the social media platforms have far greater access and powers to crack down on this stuff,” he says.
The call has also been backed by business leaders including AMP chief executive Blair Vernon, which was endorsed by a Professional Planner editorial.
The financial advice profession
O’Halloran says lead generation is not mainstream in the advice sector, but that does not limit the damage. “It only needs to be a few operators for them to be able to sign people up at scale.”
He says Super Consumers had been talking with the Financial Advice Association Australia about the Government’s proposal. “I know that they have concerns about how the government’s proposal would actually be implemented.“
Phil Anderson, general manager policy, advocacy and standards at the FAAA tells Professional Planner it is strongly opposed to lead generation based on cold calling and aggressive sales tactics and welcomes decisive action in response to the Shield and First Guardian collapses. Members are deeply concerned by misleading statements, lead generators doing work that should be done by financial advisers, and lead generators taking a high proportion of the fees clients may pay for any resulting advice, he says, as well as by social media’s role in exposing consumers to this misconduct. Action should not, however, interfere with genuine referral arrangements, including referrals from super funds or from professionals such as accountants and lawyers, which should remain a legitimate pathway to advice.
O’Halloran’s message to advisers: “A lot of advisers are doing the right thing. I think they should keep calling out bad practice in their sector when they see it, and keep driving towards professionalisation, because I think it harms the reputation of all of them.”
What happens next
Although the review covered only 15 licensees, lead generation accounted for about 35 per cent of their new clients over the 18 months to June 2026. The $678 million invested works out to an average of about $89,000 for each of the 7,639 clients referred. How the Government’s proposed reforms, announced in August, respond to activity on this scale remains to be seen.
ASIC said it will keep monitoring compliance and act against licensees and representatives where appropriate. It will work with Treasury on the Government’s reforms, announced by Assistant Treasurer Daniel Mulino on 19 August, to curb harmful lead generation. The proposals include restrictions on real-time contact with consumers about superannuation by unlicensed parties, stronger consent and anti-hawking requirements, and enhanced licensee oversight. ASIC says it welcomes them. They remain proposals, not enacted law.
ASIC has already taken related action, including Federal Court proceedings against Imperial Capital Group Australia and proceedings against Clark Family.


Leave a Comment
You must be logged in to post a comment.