


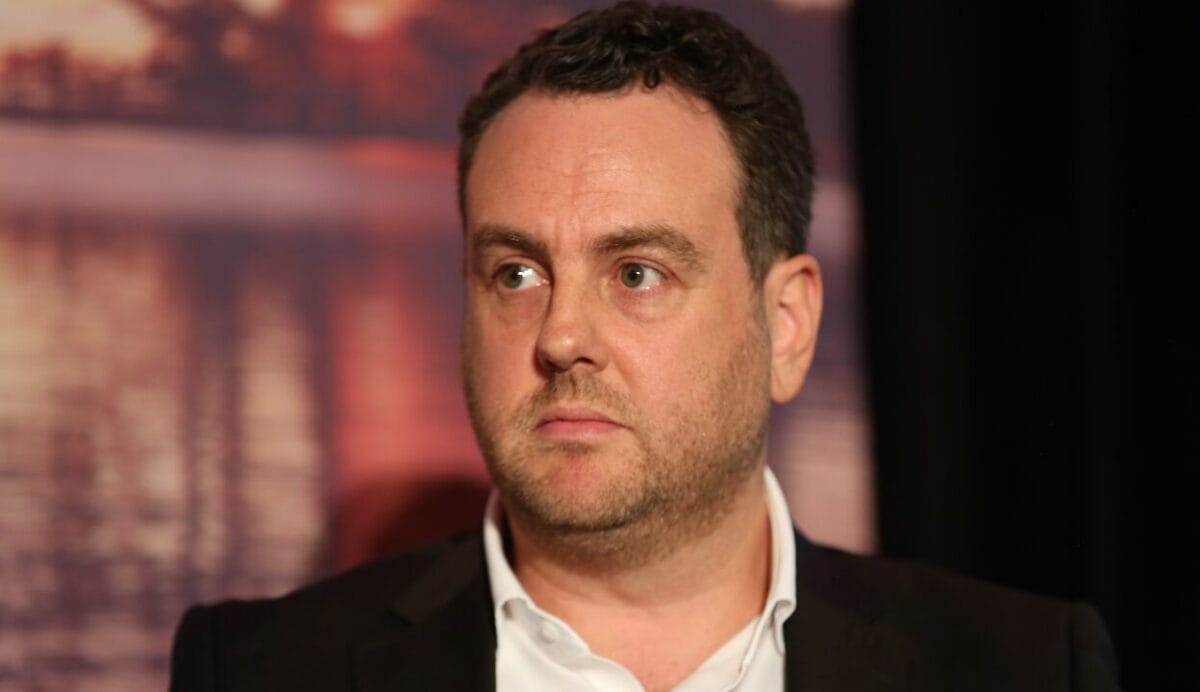
Minister for Financial Services Daniel Mulino has revealed the Albanese Government will expedite measures to boost access to financial advice including changes to mandatory education requirements for advisers and the best interests duty safe harbour.
Mulino on Thursday said the measures outlined in his National Press Club address in August will be split into “at least three” tranches and introduced to Parliament next year. The revelation dashes any hope of a shock introduction of the financial advice policy measures in the final sitting dates of the year.
However, the minister also made clear that measures to boost the supply of professional advice including the much-anticipated changes to education standards were his highest priority and were even higher in the queue for legislative drafting than consumer protection provisions relating to the $1.2 billion collapse of the Shield and First Guardian master trusts.
“Advice is incredibly important and so I want to do whatever it is that I can do to improve access to advice,” Mulino told the AIOFP national conference in Adelaide. “The number of announcements made at the Press Club mean that we’re going to have multiple tranches of legislation. I suspect it will be at least three. And really, for me, it’s a matter of trying to figure out what are the priorities. I’m really trying to push this as quickly as possible.”
Mulino listed “education pathways” and “scaled advice” as relatively uncontentious policy proposals on his agenda that would be earmarked as priority. The education pathway changes were first announced by his predecessor Stephen Jones at the inaugural Professional Planner Advice Policy Summit in 2025.
A consultation on the proposed changes – under which new entrants would need a bachelor’s degree or higher in any discipline, rather than a prescribed financial advice degree under the old FASEA regime – ended in April. Although there are some disagreements on design and timelines, the measures are broadly supported by the relevant industry associations.
“I think there is a way forward where we can maintain appropriate standards but make it easier for people coming into the profession to satisfy those education [and] training obligations,” Mulino said.
The scaled advice reference is presumably a nod to the announcement that the government would remove the “catch all” so-called step (g) in the safe harbour provisions in the best interests duty legislation, which it believes has held up forms of scaled and digital advice to consumers.
It is understood some product providers have been actively lobbying for removal of (g), although some lawyers are unconvinced it will have the desired effect in practice, with commercial firm Allens describing the measure as a “minor tweak” and Holley Nethercote’s Paul Derham questioning the conclusion that the change would result in a boost for scaled advice.
Capital compensation
While these “not overly complex” measures would be prioritised, Mulino listed the announcement of new capital requirements for platforms as an example of a “more complex change” that would likely take more time to draft and legislate.
But he said the government remained committed to the proposal, which would allow the prudential regulator to set capital requirements so trustees offering “higher-risk options” will be able to compensate members for capital losses without these matters coming before the Compensation Scheme of Last Resort.
“What we saw with Shield and First Guardian was that two of the four platforms paid out, in terms of the capital that was invested, we saw that with Macquarie and Netwealth, investors got their capital back,” Mulino said.
“If that had happened with all four of the platforms, we would be in a very different position. Consumers would be in a better position but also the financial services sector as a whole would be in a better position.
“If platforms know they’re going to be … more accountable, they will undertake better due diligence of the kinds of products they put up on the platforms.”
The comments come amid a raft of changes to the regulation of platforms in the wake of Shield and First Guardian. Separate to the legislative reforms being pursued by Mulino, ASIC has issued regulatory guidance on financial advice fee caps by super trustees and platforms, while APRA has embarked on a body of work on investment governance for platforms.
It also comes as large corporate advice providers including AZ NGA put commercial pressure on platforms to reduce fees and forfeit control of client data.
The path ahead for financial advice reform will take centre-stage at the Professional Planner Advice Policy Summit 2027 at Old Parliament House Canberra. View the agenda or register here.



Leave a Comment
You must be logged in to post a comment.