


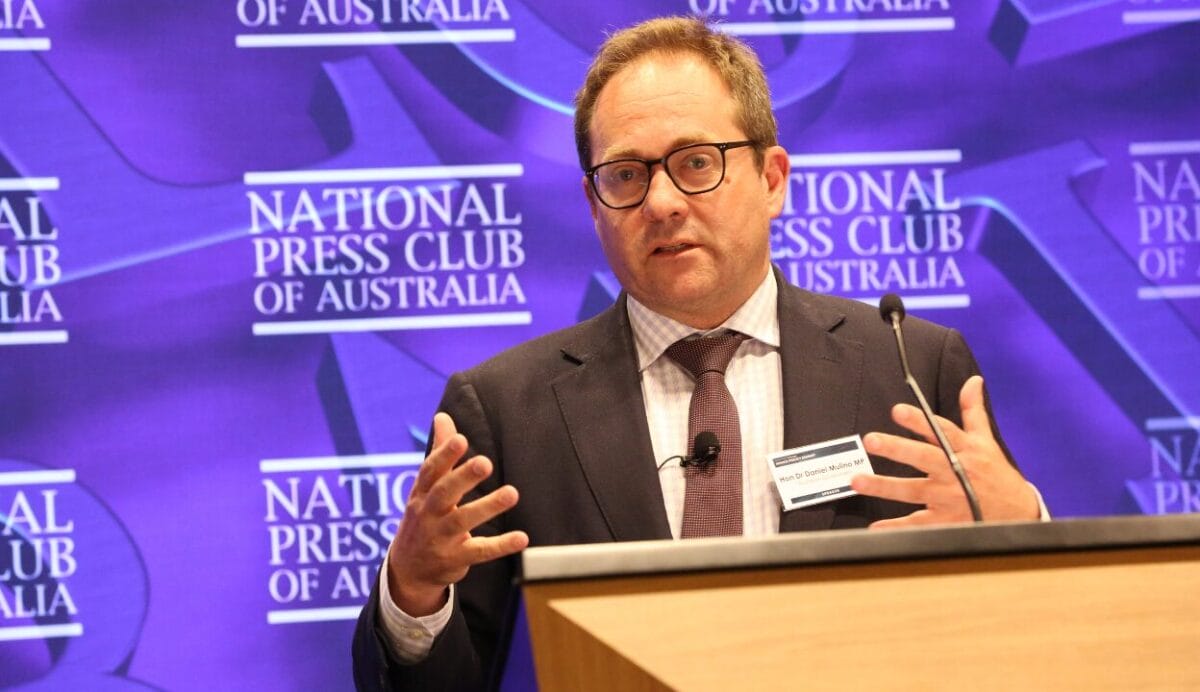
The federal government will introduce legislation next week to clarify the framework for intrafund advice charging, according to Assistant Treasurer and Minister for Financial Services Daniel Mulino, while regulatory loopholes that have allowed the creation of pension boost products will be closed.
Mulino told the Association of Superannuation Funds of Australia Conference on Thursday that the bill would clarify the boundaries of the intrafund advice, “empowering superannuation funds to provide collectively charged advice on retirement issues, subject to existing safeguards such as the Best Financial Interests Duty”.
“We know that existing regulatory arrangements have sometimes made it difficult for superannuation funds to answer relatively basic questions from their members. And that is not necessarily to the advantage of those members,” he said.
“We need to ensure Australians can obtain meaningful assistance at important points in their financial lives, without compromising consumer protections.”
Intrafund advice charging was among the Delivering Better Financial Outcomes measures Mulino announced progress on at the National Press Club in August, along with targeted superannuation prompts, streamlined statements of advice and a new class of adviser initially limited to APRA-regulated super funds and life insurers.
Pension boost changes
Mulino also announced changes to the Age Pension assets test treatment of innovative retirement income streams, after Treasurer Jim Chalmers took aim at the “unintended and expensive consequences” of so-called “pension boost” products.
In his speech, Mulino said that only 60 per cent of the assessed value of these products is counted under the assets test, and that concession would be retained, but that the government will change how the products are valued, using their actual value at retirement in place of Social Security deeming rates as a proxy for investment earnings.
“Because those rates can be substantially lower than actual investment earnings, a growing difference can emerge between a product’s actual value and the value recognised under the assets test. The earlier someone purchases one of these products, the greater that difference can become,” he said.
“The result is that some retirees can receive additional Age Pension payments, not simply because of the intended concession, but [also] because the assets test understates the value of their retirement savings. Indeed, this feature has sometimes been marketed as an Age Pension boost.”
Mulino said the cumulative effect of the valuation differences could place growing pressure on the Age Pension as the products become more widely available.
“We support innovative retirement income products. We support appropriate concessions that recognise their characteristics. But we do not believe that innovation should depend on unintended advantages in the Age Pension means test,” he said.
“Nor should retirees with comparable financial circumstances receive materially different levels of government support simply because of the way a particular product is valued.”
Income stream rules
The government will also consult on changes to the superannuation income streams regulations, which Mulino said were aimed at supporting products that provide a guaranteed income for life.
Under the proposed changes, providers would be able to offer a money-back guarantee that fully refunds a retiree’s initial contribution on death, and products purchased through instalments would receive more neutral treatment relative to a single upfront contribution.
The government is also consulting on recognising a couple’s joint life expectancy, rather than only that of the primary beneficiary, for products that provide income to a surviving partner, and on transfer balance cap issues that arise when a reversionary product passes to a surviving spouse.
“I don’t believe the role of government is to prescribe a single retirement product that every Australian should use,” Mulino said.
“Our role is to establish a regulatory framework that supports a range of high-quality options, with appropriate consumer protections, so Australians can make decisions that reflect their own circumstances.”





Leave a Comment
You must be logged in to post a comment.
Login via LinkedIn