


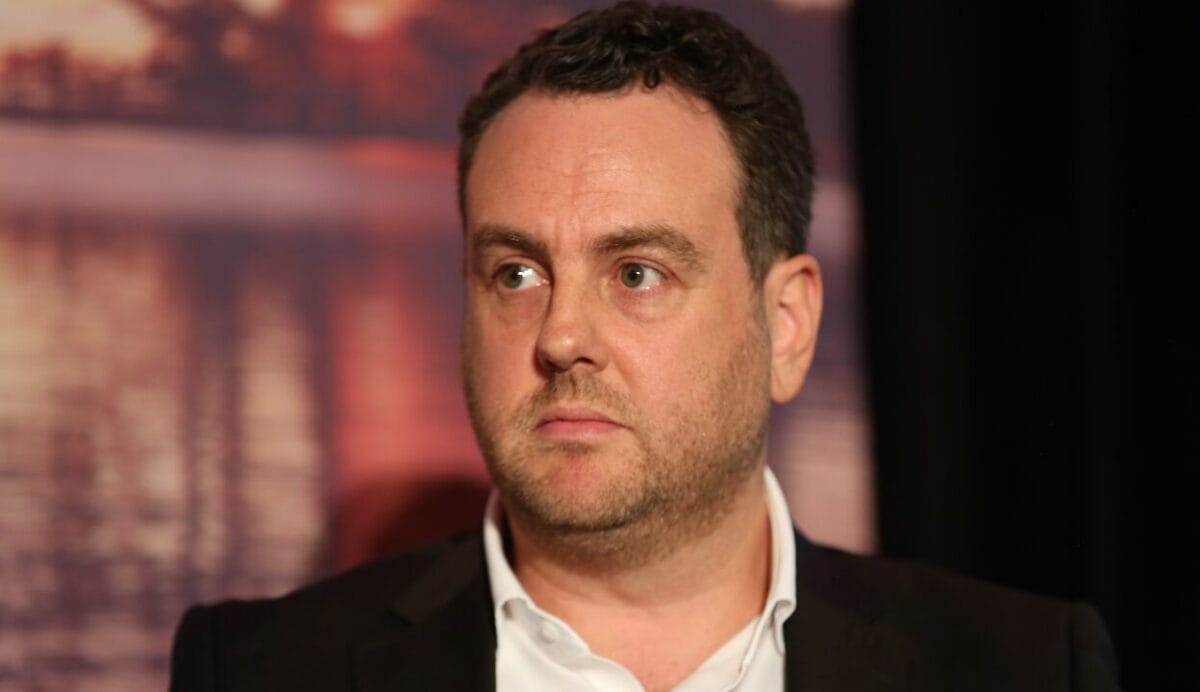
Lawyer Paul Derham, managing partner at Holley Nethercote, calls removing paragraph (g) a step in the right direction, but not one that will unlock scaled advice or new business models aimed at the mass market.
“I already thought people could easily give scaled advice with (g) in existence,.” Derham says regarding the government’s plan to drop the last step of the best interests duty safe harbour.
On 19 August, Minister for Financial Services Daniel Mulino announced targeted reform of the Best Interests Duty to enable scaled advice, and Treasury’s fact sheet casts (g) as a barrier to it. So is the problem the law or the practice? And if (g) goes, will it be the file or the fee that changes?
Paragraph (g) is the last step in section 961B(2) of the Corporations Act, the list of steps an adviser can follow to show they acted in a client’s best interests. It asks the adviser to take any other step that would reasonably be regarded as being in the client’s best interests, given the client’s circumstances.
It is understood that many product providers including platforms and insurers have been lobbying for the removal of (g), along with a handful of major licensees.
Under the announcement, steps (a) to (f) stay and so does the duty itself. That is narrower than the earlier policy intention to scrap the safe harbour steps altogether, as the Quality of Advice Review recommended.
The change sits in a wider package announced by Mulino at the National Press Club: streamlined Statements of Advice, clarity on intra-fund advice topics, a New Class of Adviser for super funds and life insurers, streamlined education requirements and a review of the Code of Ethics.
Mulino’s office and Treasury officials are currently believed to be working on a draft of the legislation, widely expected to be introduced following the resumption of Parliament in 2027.
Derham’s argument departs from the Government’s core premise.
“I already thought people could easily give scaled advice with (g) in existence,” he says.
The Super Members’ Council, which represents industry and profit-to-member super funds, argued retaining paragraph (g) of the Best Interests Duty safe harbour provision helps ensure advice is not reduced to a checklist exercise and that scaled advice can be delivered successfully under its requirements.
Asked whether the SMC is right that the law already allows scaled advice and (g) is not the problem, Derham answered: “Yes, that’s right.”
Derham tells Professional Planner (g) asks no more than professional judgement. His analogy is a doctor asked to treat a chest infection who notices a cyst on the patient’s neck. The doctor does not have to treat it, but a professional would mention it and let the patient decide. Under (g), he says, an adviser does the same: flag the others need, and the client can say no.
‘Playing around the edges’
Nor does he expect the change to matter in practice. “I’m not aware of a single case where an adviser has got in trouble because they’ve done everything right, but they haven’t satisfied (g),” he says. ASIC will keep asking about the other steps and reading the whole file, and removing (g) “changes a little bit of playing around the edges”.
What will decide an adviser’s fate, he says, is proof. “To meet the Best Interest Duty, you always need to be able to evidence what you’ve done, whether you’re a lawyer or a doctor or an adviser.”
His real objection is to the checklist itself. He wants advisers treated as professionals under an overarching duty, and the safe harbour gone. “Do we treat them as professionals, or do we treat them as workers that we need to check every step?”
The winners, he suggests, are compliance and risk heads at funds, insurers and licensees, who face slightly less regulatory risk if advisers are no longer expected to pick up every outside issue.
His advice to licensees is to wait. “We wouldn’t tell people to change anything at this stage. We’d wait for the legislation.”
The Quality of Advice Review, headed by former Allens partner Michelle Levy, recommended a new duty with no safe harbour. Her final report argued that removing the safe harbour would let advisers scale their advice by not assessing available products, saying it is “the best interests duty rather than the safe harbour which makes it difficult” to advise on a single product.
Her point is about product recommendations, not step (g), and she treats the difficulty as a question for the review’s later chapters. The government has kept the duty and is removing only (g).
On Derham’s claim that the professional standard is enough, ASIC’s November 2025 review of 100 SMSF establishment advice files found 62 could not show compliance with the best interests duty and 38 could. ASIC selected the files on risk, so the result is not an industry-wide rate, and it is about the duty as a whole, not step (g). Still, it complicates the argument that advisers can safely be trusted as professionals without prescriptive steps.
Levy will be speaking at the Professional Planner Advice Policy Summit at Old Parliament House Canberra on 23-24 February 2027. For more information visit see the full agenda.


Leave a Comment
You must be logged in to post a comment.