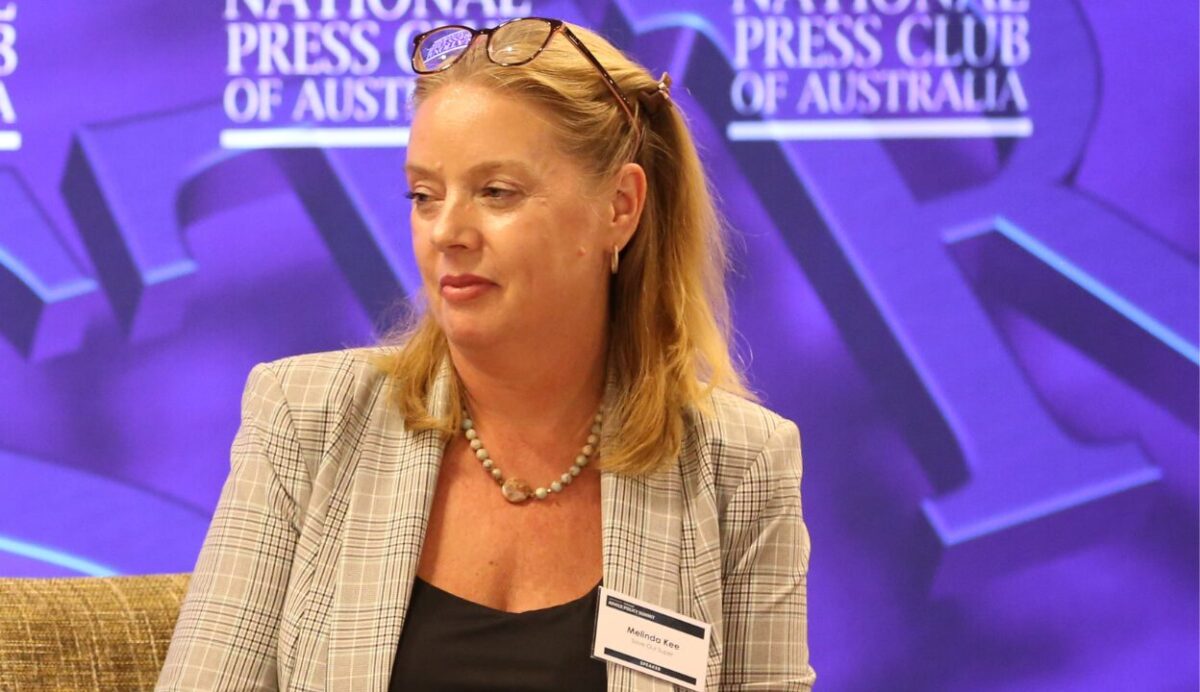
Shield and First Guardian investor advocate Melinda Kee says a class action against Macquarie Investment Management is likely to produce a worse outcome for victims of the collapsed Shield master fund than the path already open to them through the Australian Financial Complaints Authority and the Compensation Scheme of Last Resort.
Gordon Legal commenced the class action in the Supreme Court of Victoria on 16 September, on behalf of representative plaintiff Rachelle Dessent and around 2800 investors who put about $321 million of their superannuation into the collapsed Shield Master Fund through Macquarie’s platform.
It seeks additional compensation for investment growth these investors missed out on, and for distress suffered as a result of the collapses. Shield and First Guardian combined have left close to 11,000 investors with about $1.2 billion at risk.
Another platform operator, Netwealth, compensated investors in another failed managed investment scheme, First Guardian, to the tune of $100 million on a similar basis.
Earlier this week, Netwealth informed the ASX that it had received a letter from solicitors acting for a proposed representative plaintiff “alleging breaches of duties in connection with the offering and monitoring of certain First Guardian investment options available through the Netwealth Superannuation Master Fund”.
It said the proposed claims relate to matters “previously addressed through Netwealth’s court-enforceable undertaking with ASIC and the compensation program completed in January 2026”. No proceedings have yet been filed.
Kee says it is far from certain how long it will take to settle the Macquarie class action, and the amount of compensation that ultimately flows to Shield victims is equally uncertain. Kee says it is likely to be significantly less than investors might receive through AFCA.
“Gordon Legal will take 20 to 25 per cent to repay the litigation funder that is financing the class action”, Kee tells Professional Planner.
“Then they will take out their legal fees and expenses [and] the investors end up with the breadcrumbs.”
Complaint against a trustee
Gordon Legal says on its website it is taking action against Macquarie because investors themselves are unable to bring a complaint at AFCA against a trustee, but Kee says “the lawyers have to know that [investors] may not be able to file a complaint against the trustee, but they can file a complaint against the licensee, whom their financial adviser fell under, that gave them the advice to go into these funds”.
“Macquarie and Netwealth stepped up before Christmas for these victims, and… let’s say they’ve given back their net investment to these victims. And the responsibility for the balance should fall on the licensee, who ultimately failed in their due diligence. Also, and I don’t believe the trustees should wear 100 per cent liability.”
“Interprac still have PI insurance, and there is still a cross guarantee between Sequoia and Interprac. So it is very likely that there will be the funds… to compensate a good percentage of victims through those PI insurances, and then obviously there is the compensation scheme of last resort.”
Kee says the average investor in Shield is down between $77,000 and $120,000 which is well below the scheme’s compensation cap. Some investors may be down more than the scheme is able to compensate.
Investors tempted to join the class action in the hope of effectively being compensated twice for the same loss may be disappointed.
Professional Planner understands that the current CSLR legislation does not provide for compensation from the scheme to be reduced by the amount of compensation received by an individual from other sources.
Any offset in compensation must be set out in a determination issued by the Australian Financial Complaints Authority. In some cases the quantum of compensation an individual has received from outside AFCA is known to the authority when it makes a determination.
But the outcome of a class action, which potentially could take many months or years to settle, is uncertain anyway, and may not be known to AFCA. In this situation it is conceivable that the authority might be forced to pause determinations until the outcome of a class action is known.
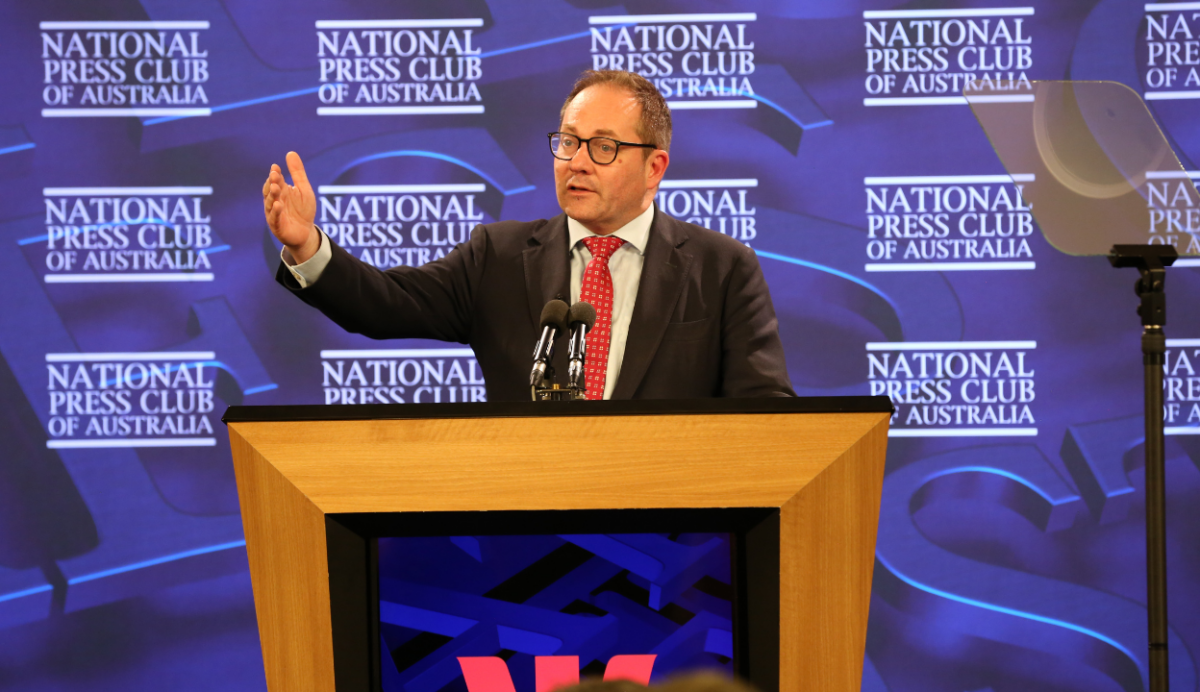
CSLR chief executive officer David Berry tells Professional Planner the scheme is “still investigating the implications of a class action”.
“We certainly know the intent is to ensure there’s no overpayment of compensation, or double payment,” Berry says.
In a statement provided to Professional Planner, AFCA said that “a class action does not automatically prevent someone from making a complaint to AFCA”.
“Whether there is any impact on an AFCA complaint depends on the circumstances of the individual complaint, including the issues raised and the parties involved,” it said.
“AFCA has considerable experience dealing with complaints where a consumer may also have access to compensation through another process.
“Where that is the case, an AFCA determination can take the potential for other compensation into account.”





Leave a Comment
You must be logged in to post a comment.