
“Never a truer word than spoken in jest,” or something like that, is an old cliché but it’s still relevant. A “hypothetical” session at the end of Wednesday’s opening day of the SMSF Association conference demonstrated at least a few examples of the truth wrapped up in humour.
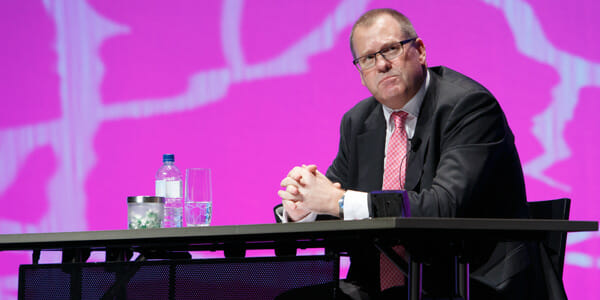
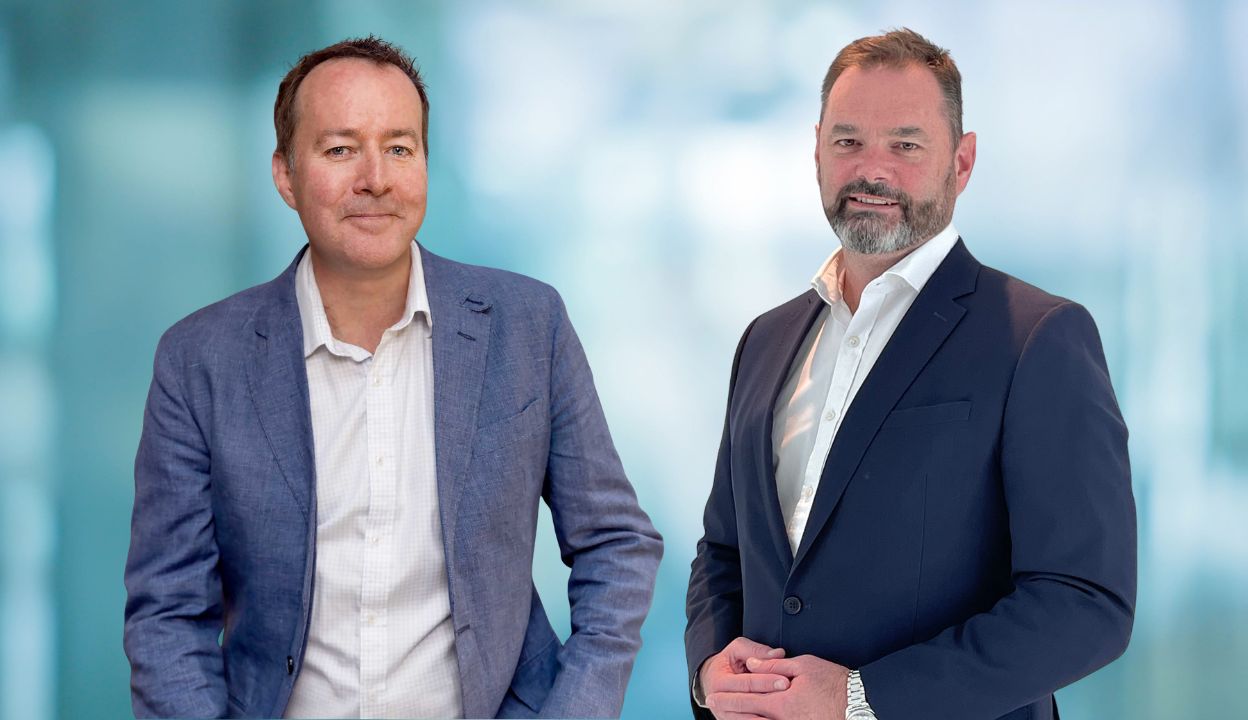
That’s the whole point of such a mock debate, but the irony is worth noting nonetheless. A number of well-respected industry figures played the parts of Devil’s advocate (Russell Mason, Deloitte, pictured), pro-regulation (Andrew Gale, Chase Advisory), the lunatic fringe (xxxx) and consumer interests (Craig Meldrum, Australian Unity).
The moderator, finance journalist Michael Pascoe, asked a question: “So, professionalism. If you’re the sole super regulator, couldn’t you just demand it?”
Mason’s response was an emphatic “yes”, saying he was done with “spending years going back and forth to associations” on what professionalism means and how to achieve it.
The financial planning sector has long been hamstrung by a lack of consensus among those who purport to represent them, namely the professional and industry associations. While the largest two associations have agreed on some points, they collide over far too many.
Do we ever see the doctor’s Australian Medical Assocation – or the accounting profession’s Institute of Chartered Accountants and Certified Practicing Accountants Australia at loggerheads? I’m sure they do disagree, but not publicly. They sort out their issues behind closed doors and then come forward with a united, cohesive argument.
Perhaps the most recent example of dissent for the two financial planning associations was over the troubled life insurance advice sector. One association was a key driver of the Life Insurance and Advice Working Group (LIAWG), along with the Financial Services Council. The other association wasn’t.
Whether or not the overall LIAWG review is flawed – as implied by the blatant snub by ‘the other’ association – is beside the point. If all stakeholders are really serious about progressing into a profession and about building consumer confidence in planners, the decision on whether to run the review or not should have been contingent on having consensus from all players.
Anything less, and the whole process – and industry reputation – suffers.
Another point from the SMAFA conference “hypothetical” session also rang true. An argument the in-character Mason put forward for a single, almost-despotic regulator, dubbed “Superlator”, is the confusion created by a “multitude of regulators in ASIC, APRA, Austrac”.
Having a single regulator responsible for all the areas these covered would be a step back in time to the UK’s old regulator, the Financial Services Authority. In the present day, real-world Australian financial industry, commentators have called for a separation of life insurance “advisers” and financial planners. This sounds suspiciously like a step back to life agents and brokers – a flawed, sales-based model abandoned years ago.
To end on another cliché: “Those who cannot remember the past are condemned to repeat it”.


Leave a Comment
You must be logged in to post a comment.