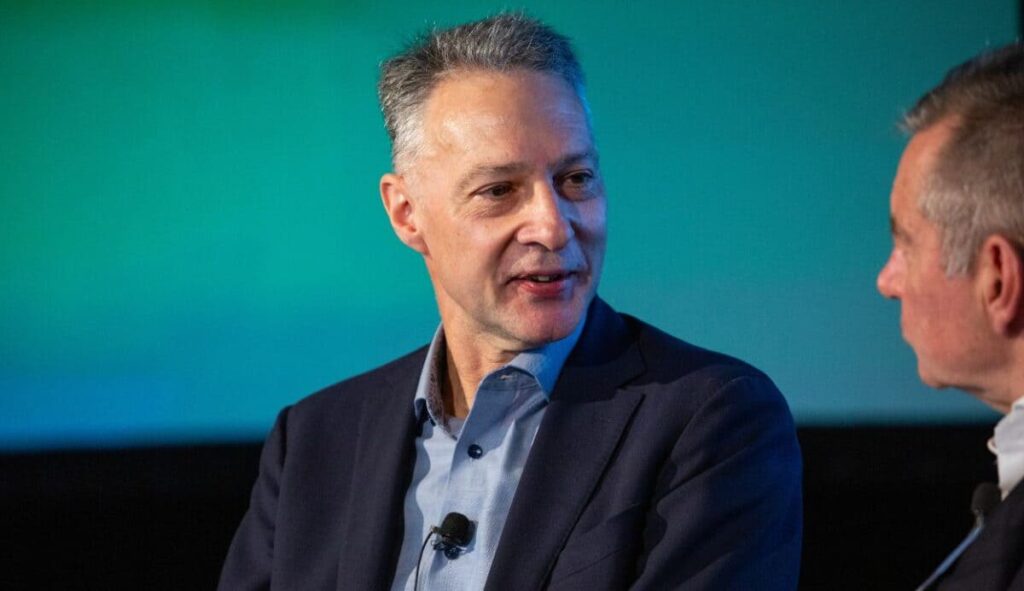
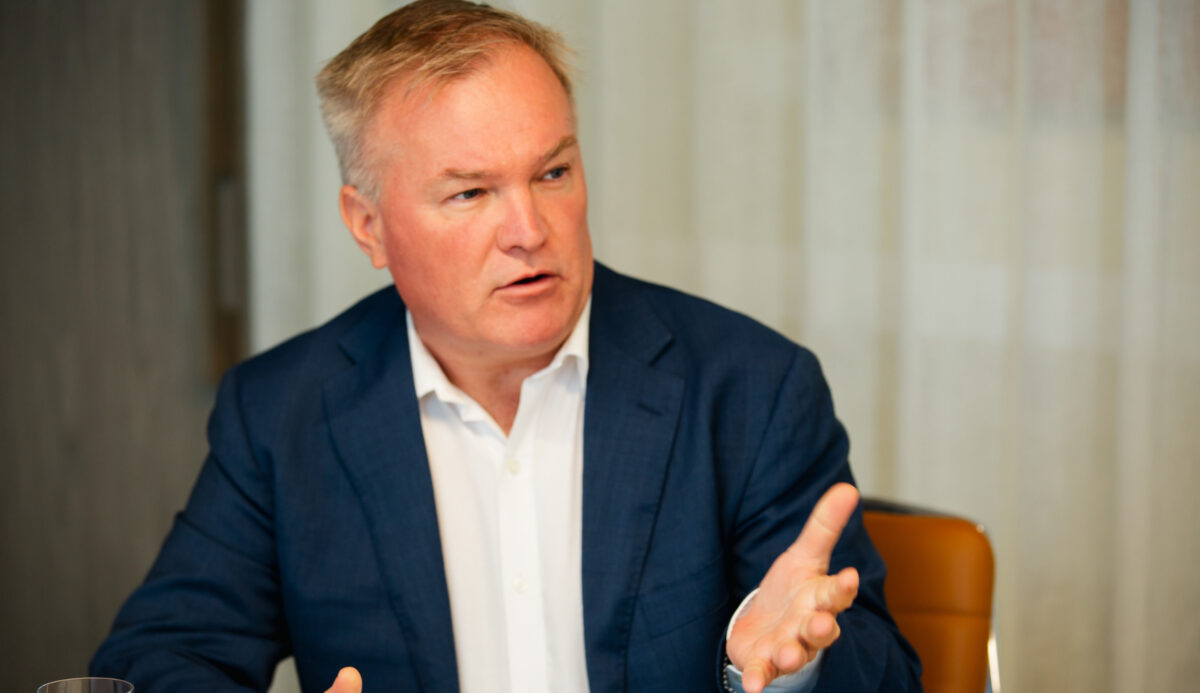
The UK’s largest workplace pension scheme by members, will launch a default retirement product within the coming years that puts around 15 per cent of a member’s pot into a deferred annuity and tells them how much they can sustainably draw from the rest, according to Nest Invest chief executive Mark Fawcett.
The scheme, which invests on behalf of 14 million mostly low-to-moderate income workers, designed its “retirement blueprint” after the UK scrapped effective compulsory annuitisation in 2015, but was blocked from launching it until now.
“It’s a combination of a drawdown portfolio for the first, say, 20 years of retirement, and then an annuity for the rest of your retirement, whether that’s one year, 10 years, 15 years,” Fawcett told the Investment Magazine Fiduciary Investors Symposium in Healesville last week.
“For a variety of reasons, including concerns from the UK insurance industry, we didn’t have that permission to launch a product, and so we’ve now been finally given the permission.”
The UK’s Pension Schemes Act 2026, which received royal assent in April, requires trustees of defined contribution schemes to offer a default “guided retirement” pathway or transfer members to a scheme that does, similar to Australia’s Retirement Income Covenant. Nest has also recently been allowed to offer “flexi-access” drawdown, which Fawcett described as a “stepping stone” to the blueprint.
“The problem with flexi-access drawdown, which I guess you have here, is people don’t know how much they can sustainably withdraw,” he said. “So our product will consider what is a sustainable withdrawal rate and pay out a stable income, because most people in the UK won’t take advice or can’t afford advice, and maybe not unreasonably [fear] questionable quality, bad advice.
“It’s our job as trustees, with our fiduciary duty, to help them by telling them what we believe a sustainable withdrawal rate is, and that way they can optimise their retirement, because the risk is they don’t take enough out, or they take too much, so they run out of money or actually live a less good quality of life than they could.”
Fawcett said that fixing the investment horizon was the first step towards reconciling sequencing risk, longevity risk and income maximisation for members who don’t receive financial advice.
“This has been described as the hardest problem in investment, right? Decumulation,” he said. “We’re working with an insurance company to basically put about 15 per cent of the member’s pot into a deferred annuity. They retire at 65. We buy the deferred annuity at 75. It starts paying out at 85. So we’ve got a 20-year investment window, as opposed to an unknown-length investment window, so that makes it easier.
“You’ve still got the sequencing risk, and so that’s the question of how you invest. One of the things we’re thinking about is actually: is there space for private markets, more stable income-generating assets, even in retirement, which is traditionally ‘oh, you’ve got to be all liquid’.”
“Given the cohorts we have and all the cash flow we have, we think we can put in income-related infrastructure, real estate, even short-term private credit, and actually that will stabilise returns and reduce the drawdown, the sequencing risk. You can’t eliminate it. We war-game when we would have to cut income. But it’s easier for us to do it than it is for a member.”
Fawcett said the same problem exists in Australia’s industry fund sector, but that Nest was keen to help solve it.
“Everything I hear talking to Australian industry funds is that’s a bit of the same problem exists here. We’re very happy to share our work, and if people want to think about how to provide those retirement products, we’re happy to help.”


Leave a Comment
You must be logged in to post a comment.