The experience of the suit-tailoring industry contains a stark warning for financial advisers: when a long-established bespoke trade mistakes disruptive technology for a productivity tool, change can remain barely noticeable until it suddenly explodes.
AI is already moving through financial services, compressing costs, removing friction and challenging assumptions that once felt safe. Commentators reassure advisers that AI is a productivity enhancement and the personal relationship will remain king. That is a risky assumption.
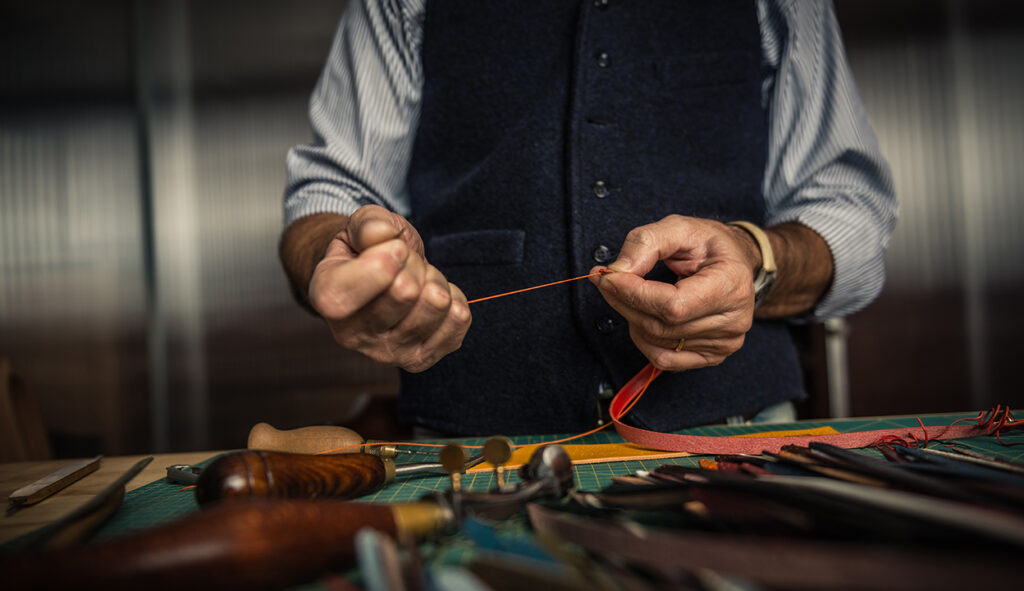
A family story illustrates the danger. My father-in-law was a bespoke tailor in Adelaide for more than 40 years, one of the best in Australia. Prime ministers and business luminaries were among his clients. His was a hand-made craft built on quality, customised fit and individual service, which will sound familiar to most advisers. He even had a cheeky sign that said, “We fix cheap Hong Kong suits.”
Advances in materials and machinery improved productivity, but the central premise of bespoke tailoring stayed the same. By the late 1990s he had closed the business, unsalable because he had not adapted. People had not abandoned suits. What changed was how they were made, sourced, distributed and bought, and the price customers would pay. Within 15 years, many were willing to accept a substitute 80 per cent as good at a price 70 per cent lower.
Offshore manufacturing, such as in Fiji, flooded the market with reasonable quality at much lower prices. Today only a handful of bespoke tailors remain, serving the few willing to pay a princely sum for the prestige. Advisers face a similar reality from AI.
Productivity, substitution, reinvention: For decades, advice has been one of the most human and relationship-led parts of financial services. Firms are using AI to automate administration, scale personalisation and free advisers from low-value work. That is the first stage: productivity.
The second is substitution, as AI begins performing work previously sold as professional advice. The third is reinvention, when client expectations shift from expensive, cumbersome, human-led propositions to automated systems that still feel human. The danger is assuming the first stage is the destination.
The right question
Focus on the right question. The uncomfortable question is not whether AI will improve adviser productivity; it will. But the sharper question is what happens then: what clients will pay, for what; and how and by whom it is delivered. The entire business model of advice is up for grabs.
Beware the Thai saying “same-same but different”: Most practices remain cottage industries, dependent on ongoing fees and protected by fragmented systems and the treasured “relationship”. Banking, travel agencies and call centres relied on similar defences and were reshaped by technology. AI is also eroding graduate, junior and middle-tier work, which raises a second-order problem: if fewer people enter through junior roles, how will future advisers develop the judgement to oversee AI output and ensure it is right?
Friction is no longer a business moat: AI already supports work that once required a skilled adviser, such as building rapport, assessing risk preferences, modelling income needs and producing client-ready narratives. It is available around the clock and needs no premises or holidays, shifting control from the adviser to the consumer.
The profession is becoming infrastructure, embedded in the platforms consumers already use. The result is a far lower-cost operating model that can serve many more clients with minimal human labour while still feeling personal. Regulation, particularly ASIC’s requirements, may slow that transition and buy advisers time, but it is unlikely to stop it.
When the “relationship” becomes digital: Advisers argue that the relationship is the irreplaceable pillar of advice. That may remain true in emotionally complex moments such as family succession, business exits and irreversible decisions. But its everyday expression is changing quickly. AI agents can already converse naturally by phone and video, with a consistency and personalisation that can rival human service in routine interactions.
Identical to a human, sometimes better
A friend’s son, a visual AI developer in Auckland, showed me how his AI-generated humans interact in real time through speech, movement and simulated body language. They were identical to a human, and sometimes better. They do not reproduce human judgement or genuine empathy, but they replicate the signals clients interpret as the AI empathising, communicating and responding perfectly, by mirroring the preferences of the person its engaging with. These skills can take an adviser years to develop.
“Fake-real” people: I recently made a restaurant reservation in Sydney by phone and believed I was speaking to a person. Only at the end, after natural pauses and hesitations, was I told it was an AI agent. This is substitution.
More significantly, services such as Replika and Character AI offer AI companionship, and some have explored recreating lost loved ones from photographs, videos, texts and emails. Users knew the “person” was not real but would not stop, and some in an early pilot even sued to keep the service. That makes “the relationship is king” both true and dangerous. The relationship may not disappear, but a human adviser may no longer be needed to deliver most of it.
Margin compression comes for advice: Advice has been the last bastion of generous margins. Asset management, administration, custody and execution have faced immense fee pressure, but advice has been insulated because it is relationship-led and hard to scale. AI challenges both protections. In Australia, compression is likely to emerge first in superannuation, research, life insurance and direct investment platforms.
The adviser’s strategic choices: For those nearing exit, the message is pragmatic: prepare before the wave arrives, while practice-sale multiples still hold. Valuations are likely to fall once AI-enabled competitors prove superior.
For newer advisers and growing firms, the response is to run towards the technology with eyes open. Take AI courses now, and do not assume AI capability can be outsourced. First, use AI to cut overhead and design the business to serve thousands rather than a few hundred. Next, automate a large share of routine client interactions. Finally, broaden the proposition beyond portfolios, products, returns and tax outcomes. Firms that stop at the first stage will have improved the old model without preparing for the one that will replace it.
The winners
The winners will not be the advisers with the strongest technical expertise or interpersonal skills. They will own services that combine AI-driven advice with behavioural insight, direct marketing and a business model linked to the rest of a consumer’s life. They will know where not to compete, leaving AI to handle routine work such as risk evaluation, product selection and compliance, and concentrating human judgement where it creates distinctive value.
Clients may move more readily than advisers expect because the new experience will be immediate, cheaper and low in entanglement: advice embedded in daily financial life, responding by voice, with no forms, no waiting and no office appointments. A few will still pay for a bespoke in-person financial tailor, but not many.
How long have you got? No one can say precisely. We often overestimate what will change in the short term and underestimate what will change over the medium term. High-street travel agencies survived far longer than many forecasts suggested, but Flight Centre recently announced it has begun rolling out AI to replace its street-front operations. AI may be the most consequential technology since electricity, and much faster. Change will arrive sooner rather than later, and competitors will come from outside the industry.
Watch super funds, direct platforms, fund administrators and research houses move first. As with tailoring, the early signs are unlikely to appear as a dramatic revolution. They will appear as better client experiences, lower prices, faster service and a quiet attrition of advisers. A trickle of change one afternoon, a flood the next day.
Grant Pearson is the founder of Pearson & Partners.


Leave a Comment
You must be logged in to post a comment.