


Produced in partnership with iShares by BlackRock.
There are many things keeping investors up at night, including geopolitical uncertainty, trade conflicts and inflation.
Another big question is, how much longer there is to go on the artificial intelligence (AI) mega trend, given that it has already been running for over three and a half years.
Since late 2022, when OpenAI launched ChatGPT 3.5, AI-related companies have become the dominant force in equity markets. BlackRock analysis shows that AI-related companies represent 47 per cent of market cap but drive 67 per cent of total earnings growth. For cautious investors who haven’t dived in yet, the concern is that they may be too late. For early movers who have been riding the AI theme higher and higher, the concern is that all the exuberance and money pouring into the sector could be creating a bubble.
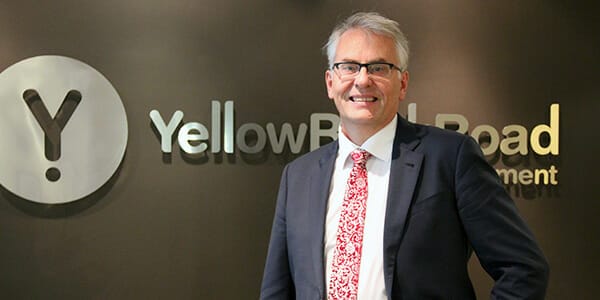
According to Lydia Vitalis, director, Australia investment strategy at BlackRock, the AI thematic is a long-term play that is reshaping the investment opportunity set and driving future returns, although performance is unlikely to be linear.
“Technology stocks have performed very strongly, and we think this will continue[VL1] [LO2] , although the opportunity is moving beyond the initial excitement of a narrow technology story to a broader infrastructure and productivity story,” she says.
“We expect the enthusiasm to shift from the technology itself, which is where it has been focused, to real world evidence of AI delivering significant productivity gains, earnings growth and return on investment.”
BlackRock has identified AI and digital disruption as one of five mega forces that are changing the investment landscape and creating big shifts in the profitability of economies and sectors.
The other four mega forces are the energy transition and resilience; demographic divergence; geopolitical fragmentation and strategic competition; and future of finance. [VL3]
BlackRock defines mega forces as big, structural changes that will affect investing far into the future. They have the power to change the long-term growth and inflation outlook and are poised to create big shifts in profitability across economies and sectors.
“We’ve identified AI as a mega force that will have long-term impacts on generating returns in portfolios,” Vitalis says.
“The technology cycle is moving faster than ever and there will be winners and losers from this, and the market leadership will rotate again, so it’s not going to be a linear or exponential outcome but the productivity opportunity set from AI is enormous.”
“This isn’t a one-year tactical opportunity, it’s a thematic that will shape the future for decades to come just like the internet changed the way people live and work. It has changed us permanently, even though there was volatility through the evolution.”
Vitalis accepts that the meteoric rise of the dominant mega cap tech stocks and the market concentration in the technology sector draws comparisons to the dot.com boom and bust of the late 1990s and early 2000s but rejects suggestions that the current AI run displays the same bubble-like risks.
She cites quantitative analysis conducted by BlackRock, which analysed hundreds of metrics and found few similarities between both periods.
“The dot.com era was marked by declining earnings quality, deteriorating capital efficiency and sharply rising valuations,” Vitalis says.
“Today’s landscape tells a story of improving earnings quality, more capital efficient companies, and valuations that are far from the extremes seen in the dot.com bubble and which have generally been better supported by revenues, profits and earnings growth.[VL4] ”
As for fears that the issues currently adversely affecting the private credit market, due to the sector’s heavy exposure to software firms, could also hit the listed equities market, Vitalis says there are fundamental differences between gaining exposure to the AI thematic through private credit versus listed equities.
“With any concentrated exposure, there are risks and that’s the flipside to the growth opportunity so it’s not a no risk option by any means, it’s just a different risk,” she says.
“If investors want to access the AI thematic through large listed companies, the questions and risks are around valuations and execution, and how AI investment converts into sustainable long-term earnings.”
Doubling down on growth
While broad market indices, like the MSCI World, S&P 500 and Nasdaq Composite, already provide meaningful exposure to the mega cap technology stocks and the AI thematic, investors looking for a more targeted growth allocation can also invest in a broad range of specialist exchange traded funds like the iShares Nasdaq Top 30 ETF (ITEK), which provides liquid and transparent exposure to some of the largest, most innovative non-financial companies in the market.
The IT sector currently represents around 77 per cent of the iShares Nasdaq Top 30. Consumer discretionary accounts for around 16 per cent and telecommunications makes up almost 4 per cent.
Despite the fund’s heavy concentration in IT and communications, the opportunity is not limited to wealth accumulators, Vitalis says.
“Many investors are seeking exposure to the broad drivers of growth and the key is the right sizing of the allocation and how it is balanced against other holdings,” she says.



Leave a Comment
You must be logged in to post a comment.